This report details the simulation of a counting process over a time interval T, where events, termed “successes,” occur independently and uniformly at a constant average rate λ. The simulation approximates this continuous-time process by discretizing the interval and analyzing the resulting stochastic model, its theoretical properties, and the interpretation of its parameters.
Rationale Behind the Discretization Approach
In many practical situations, a continuous-time counting process such as the Poisson process cannot be simulated directly from its formal definition. Instead, an effective approximation is obtained by discretizing the observation window into many small subintervals and performing independent Bernoulli trials within them. If each interval is sufficiently short, the probability of observing more than one event in an interval becomes negligible, and the resulting sequence of binary outcomes begins to mimic the behavior of a Poisson process. This idea forms the mathematical foundation for the simulation method used in this study.
Simulation Methodology
The continuous time interval T is partitioned into n small, non-overlapping subintervals of equal duration, Δt = T/n. For this simulation, we consider T = 1 and n = 5000, which yields a fine-grained discretization of the interval.
Within each subinterval, a Bernoulli trial is conducted to determine whether an event occurs. The probability of a “success” (an event) in any given subinterval is set to p = λ/ n. This probability is assumed to be small, which is a reasonable assumption when n is large. The core assumptions of this simulation are:
- Independence: The occurrence of an event in one subinterval is independent of all other subintervals.
- Small Interval Probability: The probability of more than one event occurring in a single subinterval is negligible and considered to be zero.
The total number of events, N, over the entire interval T is the sum of the outcomes of these n independent Bernoulli trials.
Accuracy of the Approximation for Finite n
Although the construction relies on the theoretical limit as n→∞, the approximation is already highly accurate for reasonably large values of n. The probability of having more than one event in a single subinterval is on the order of (λ/n)^2, so the overall probability of such an error occurring anywhere in the interval of length T is approximately λ^2/n. For values like n=5000 and moderate rates λ, this quantity is extremely small, ensuring that the discretized model behaves almost indistinguishably from a genuine Poisson process. This explains why simulation results converge quickly to the theoretical Poisson distribution.
The Approximated Stochastic Process: The Poisson Process
The described simulation is a discrete-time approximation of a continuous-time stochastic process known as the Poisson process.
A Poisson process is a counting process {N(t), t ≥ 0} that models the number of events occurring up to time t. It is characterized by the following postulates:
- Counting: N(0) = 0.
- Independent Increments: The number of events in non-overlapping time intervals are independent random variables.
- Stationary Increments: The probability distribution of the number of events in any interval depends only on the length of the interval.
- Rate of Occurrence: For a small time interval Δt, the probability of a single event is approximately λΔt, and the probability of more than one event is negligible.
In our simulation, by dividing T into n small intervals Δt = T/n, the probability of an event in each is p = λ/ n = λ( T/ n )/ T. If we consider the process over the interval T, this corresponds to λΔt. The total count of events, N, follows a binomial distribution, N ~ B(n, p).
As n → ∞ (and consequently, Δt → 0), the binomial distribution B(n, λ/ n) converges to a Poisson distribution with parameter λT. This is a classic result in probability theory known as the Poisson limit theorem. Therefore, the number of events N in the interval T is approximately Poisson distributed:
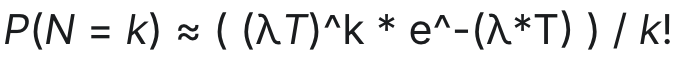
Theoretical Properties of the Poisson Process
The Poisson process, which our simulation approximates, has several key theoretical properties:
- Distribution of the Number of Events: As established, the number of events N in a time interval of length T follows a Poisson distribution with mean and variance both equal to λT.
- E[N] = λT
- Var[N] = λT
- Distribution of Inter-arrival Times: The time between consecutive events, known as the inter-arrival time, is a continuous random variable. For a Poisson process, the inter-arrival times are independent and identically distributed (i.i.d.) random variables following an exponential distribution with parameter λ. The probability density function (PDF) of the time τ until the next event is:

Interpretation of Inter–Arrival Times
An important consequence of the Poisson approximation is that the times between successive events behave like exponential random variables with rate λ. In the discretized scheme, event times are represented by the positions of successful Bernoulli trials within the partitioned interval. When the partition is fine enough, the distribution of these inter–arrival gaps becomes nearly indistinguishable from that of an exponential distribution. This connection highlights a fundamental property of the Poisson process: its memoryless nature, which manifests directly through the exponential distribution of waiting times between events.
Interpretation of the Rate Parameter λ
The parameter λ, often referred to as the rate parameter or intensity, is the central parameter of the Poisson process. Its interpretation is fundamental to understanding the process:
- Average Rate of Occurrence: λ represents the average number of events that occur per unit of time. For example, if λ = 5 and the time unit is hours, it means that, on average, 5 events are expected to occur every hour.
- Instantaneous Probability: For an infinitesimally small time interval dt, the probability of an event occurring is λdt. This reinforces the idea that λ governs the likelihood of an event happening at any moment in time.
In the context of the simulation, setting p = λ/ n ensures that the expected number of events over the interval T = 1 matches the theoretical expectation of the Poisson process:

This confirms that the simulation is correctly calibrated to model a process with an average rate of λ events per unit time.
Connection to the Theoretical Poisson Process
Overall, the simulated counting process closely reproduces the defining characteristics of a continuous-time Poisson process. The total number of observed events over the interval follows a distribution that converges to Poisson(λT), the increments over disjoint subintervals behave independently, and the waiting times between events approximate the exponential law with mean 1/λ. These empirical features confirm that the discretized construction is not merely a numerical trick but a faithful representation of the underlying stochastic process.
Visual Analysis of the Simulated Counting Process
To better illustrate the behavior of the discretized counting process and its convergence toward a homogeneous Poisson process, the following figures present two example simulations for different rate parameters, namely λ=4 and λ=16 over the interval T=1.


Example 1 — Rate λ=4
The top plot shows the cumulative number of events N(t) as a step function. Since events occur independently with probability p=λ/n in each subinterval, the resulting trajectory exhibits jumps at random times, reflecting the discrete approximation of the Poisson counting process.
The bottom plot displays the empirical distribution of inter-arrival times, compared with the theoretical exponential probability density function f(t)=λe^(−λt). While some variability and discretization artifacts are visible (particularly due to the finite number of subintervals), the observed distribution aligns reasonably well with the exponential curve, confirming the expected behavior for a Poisson process.


Example 2 — Rate λ=16
Increasing the rate parameter to λ=16 results in a substantially larger number of events within the same interval. The counting process becomes steeper, reflecting the higher expected event frequency. Correspondingly, the inter-arrival times become shorter on average, and the empirical histogram again resembles the exponential density with parameter λ.
These results illustrate how the rate parameter influences both the intensity of the counting process and the distribution of inter-event times, and they demonstrate that the discretization method successfully reproduces the qualitative and quantitative properties of a Poisson process.
Overall, the visualizations confirm that the discretized model captures the fundamental characteristics of a homogeneous Poisson process:
- Independent increments: jumps in N(t) occur randomly and independently.
- Stationary increments: the distribution of jump counts over intervals of equal length is stable.
- Exponential inter-arrival times: the waiting times between events follow Exp(λ).
- Role of the rate parameter λ: it governs both the expected number of events over time and the average spacing between them.
As the number of subintervals nnn increases, the discrete model converges more closely to the continuous-time Poisson process, reducing discretization artifacts and improving the match between theoretical and empirical distributions.
Conclusion
The simulation of a counting process by dividing a time interval T into n small subintervals and generating events with probability λ/ n in each provides a robust and intuitive approximation of a Poisson process. This discrete-time model converges to the continuous-time Poisson process as n becomes large. The analysis reveals that the number of events in a given interval follows a Poisson distribution, and the time between these events follows an exponential distribution. The rate parameter λ is the cornerstone of this model, representing the average number of events per unit time and fundamentally defining the behavior of the process.